
QRMP Monthly Payments: PMT-06 Fixed Sum vs Self-Assessment, and the IFF Cut-Off on the 13th
A QRMP taxpayer pays tax for the first two months of each quarter in Form PMT-06 by the 25th of the next month. Pay the fixed-sum challan (35% of last quarter's cash tax) and no interest applies even if the real liability is higher; a self-assessed shortfall carries 18%. B2B invoices can go in IFF by the 13th.
Quarterly returns under QRMP cut a small business's GSTR-1 and GSTR-3B filings from 24 a year to 8, but the tax still has to be paid every month. The October-December 2026 quarter is starting now, so this is the moment to decide how you will pay October's tax by 25 November, and whether your B2B buyers need their invoices uploaded by 13 November.
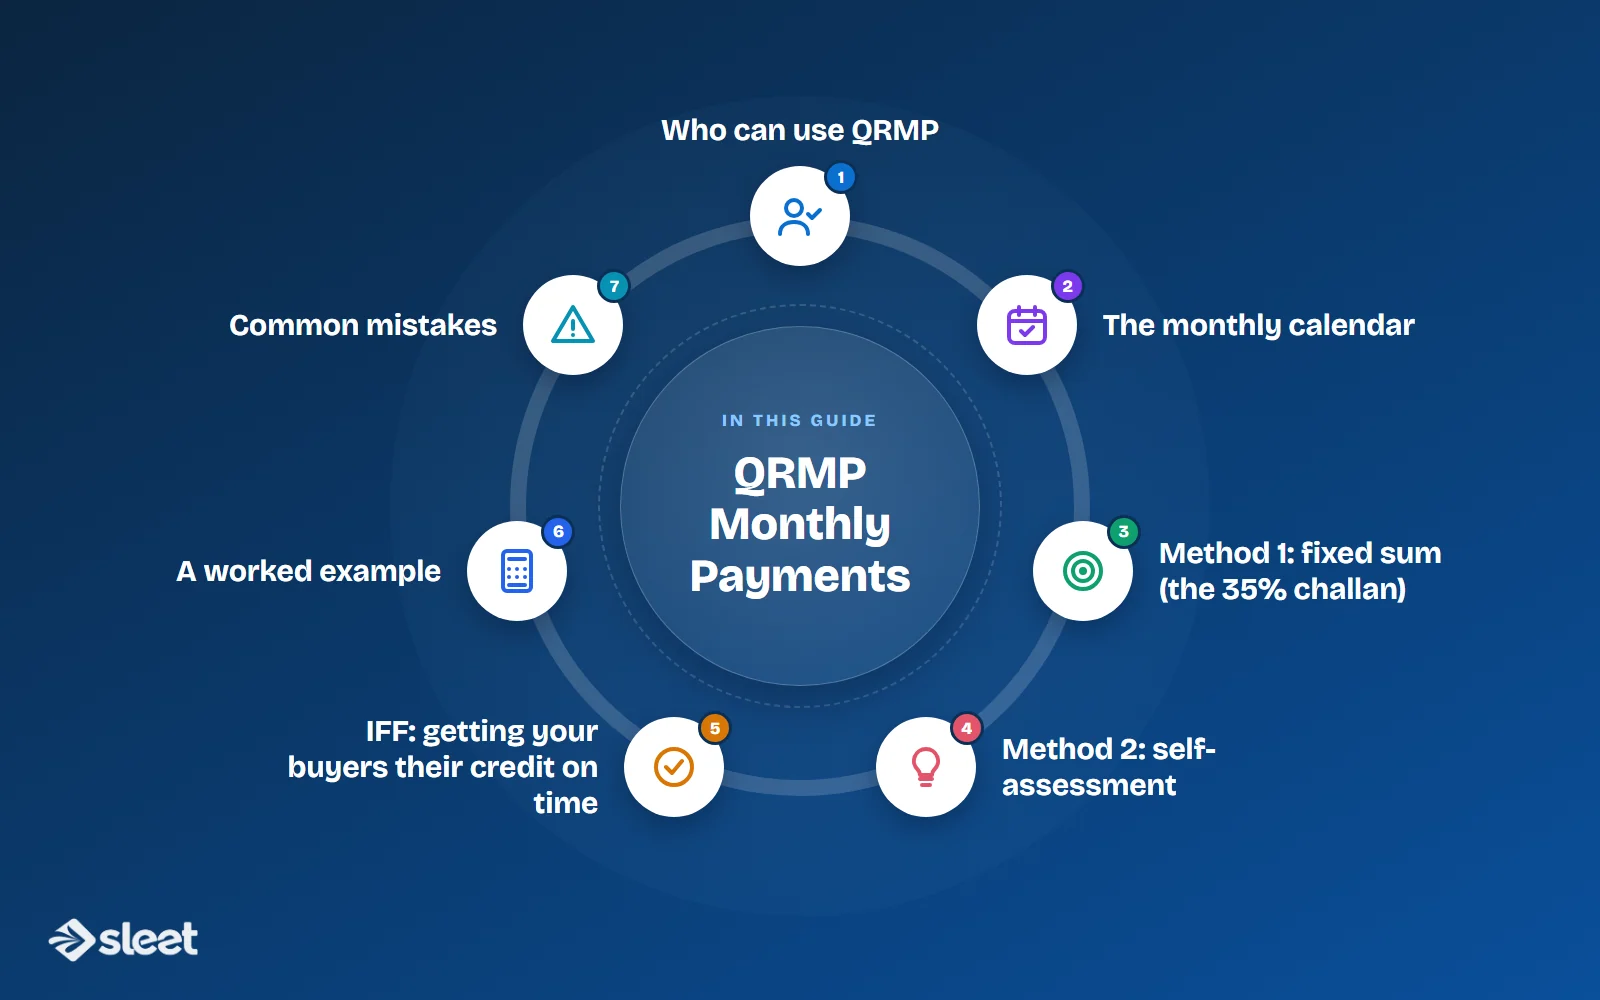
Who can use QRMP
- ✓Any registered person who files GSTR-3B and had aggregate turnover up to ₹5 crore in the preceding financial year.
- ✓If turnover crosses ₹5 crore during a quarter, you move to monthly returns from the next quarter.
- ✓The choice is made per GSTIN. One branch can be on QRMP while another files monthly.
- ✓To opt in for a quarter, use the window from the 1st of the second month of the previous quarter to the last day of the first month of the quarter. For October-December, that window closes on 31 October. Your last due return must be filed before you opt.
Once chosen, the option continues every quarter until you change it.
The monthly calendar
For the first two months of a quarter (M1 and M2) you pay tax in PMT-06. For the third month (M3), tax is paid with the quarterly GSTR-3B.
| Period | IFF (optional, B2B invoices) | Tax payment | Return |
|---|---|---|---|
| October 2026 (M1) | 1 to 13 November | PMT-06 by 25 November | None |
| November 2026 (M2) | 1 to 13 December | PMT-06 by 25 December | None |
| December 2026 (M3) | Not available | With GSTR-3B | GSTR-1 by 13 January 2027 |
| Quarter | Balance with GSTR-3B | GSTR-3B by 22 or 24 January 2027, depending on your state |
When generating the challan on the portal, choose the reason "Monthly payment for quarterly return". A monthly filer cannot use that reason.
You need not deposit anything for M1 if your cash or credit ledger already covers the month's tax, or if there is no liability. For M2 the test is whether the ledgers cover M1 and M2 together.
Method 1: fixed sum (the 35% challan)
The portal fills in the challan for you, and you cannot edit the amount:
- ✓35% of the tax paid in cash in last quarter's GSTR-3B, if you filed quarterly; or
- ✓100% of the tax paid in cash in the last month's GSTR-3B, if you filed monthly in the last quarter.
Only cash payments count. Tax set off from ITC is ignored. The method is not available to a person who has not filed a return for a complete tax period before the month.
The interest rule is the reason to use it. CBIC Circular 143/13/2020-GST says that if you deposit the system-calculated amount for each of the first two months by the due date, and pay the whole quarter's liability in GSTR-3B by its due date, no interest is charged even if your actual liability in M1 or M2 was higher than the challan. If you pay the fixed sum late, interest runs from the PMT-06 due date to the date of payment.
Method 2: self-assessment
You work out the month's actual liability: output tax minus the input tax credit available, using GSTR-2B for the credit. You then pay that amount in PMT-06.
- ✓If the amount is right and on time, there is no interest.
- ✓If you short-pay or pay late, interest at 18% a year under Section 50 of the CGST Act runs on the unpaid part from the 26th until you pay.
You can switch between the two methods month by month.
IFF: getting your buyers their credit on time
Your buyers can claim ITC only when your invoices appear in their GSTR-2B. Under QRMP, invoices you report in the quarterly GSTR-1 reach their GSTR-2B only for the third month. The Invoice Furnishing Facility (IFF) fixes this for M1 and M2.
- ✓Upload B2B invoices, debit and credit notes to registered buyers, and amendments of these, between the 1st and the 13th of the next month.
- ✓The total value of records in one month's IFF cannot exceed ₹50 lakh.
- ✓IFF is optional and has no late fee. If you miss the 13th, saved records expire and those invoices go in the quarterly GSTR-1, so the buyer waits for the credit.
- ✓Invoices reported in IFF are not repeated in GSTR-1.
- ✓There is no IFF for M3.
Large buyers often hold payment until the credit shows in their GSTR-2B. Ask your key customers whether they need IFF before you skip it.
A worked example
A wholesale dry-fruit trader in Indore, Madhya Pradesh, files quarterly. In its July-September 2026 GSTR-3B it paid ₹1,80,000 of tax in cash (₹90,000 CGST, ₹90,000 SGST). Diwali makes October heavy.
Actual net liability (after ITC) for October-December 2026:
- ✓October: ₹95,000
- ✓November: ₹50,000
- ✓December: ₹70,000
- ✓Quarter total: 95,000 + 50,000 + 70,000 = ₹2,15,000
Option A: fixed sum. The challan for each of October and November is 35% × ₹1,80,000 = ₹63,000 (₹31,500 CGST, ₹31,500 SGST).
- Pays ₹63,000 by 25 November and ₹63,000 by 25 December: ₹1,26,000.
- Pays the balance with GSTR-3B by 22 January 2027 (Madhya Pradesh is a 22nd-day state): ₹2,15,000 − ₹1,26,000 = ₹89,000.
- Interest: nil, even though October's real liability (₹95,000) was ₹32,000 more than the challan.
Option B: self-assessment, done badly. Suppose the accountant self-assesses October but pays only ₹63,000 by 25 November, and clears the ₹32,000 gap with GSTR-3B on 22 January 2027.
- Days late: 26 to 30 November (5) + December (31) + 1 to 22 January (22) = 58 days.
- Interest: ₹32,000 × 18% × 58 ÷ 365 = ₹915.
The fixed sum is the safe default for a business whose tax varies. Self-assessment suits a business with a lean month, where 35% of last quarter would lock up more cash than it owes.
Common mistakes
- ✓Choosing "Any other payment" as the challan reason. The cash sits in the ledger but is not treated as the monthly payment.
- ✓Paying a different amount and assuming the fixed-sum protection applies. The no-interest rule covers only the system-calculated 35% (or 100%) challan, paid by the 25th.
- ✓Expecting to use the M1 and M2 deposit elsewhere. Until the quarter's GSTR-3B is filed, it can only offset that return; any excess can be refunded or used after filing.
- ✓Assuming IFF has a late fee and skipping it. It has none, but your buyer's credit is delayed.
Frequently asked questions
Can I pay more than the fixed sum?
Yes. Generate a challan on the self-assessment basis for the higher amount. Everything deposited in M1 and M2 is adjusted against the quarter's GSTR-3B.
Is there a late fee for paying PMT-06 late?
No late fee applies to the M1 and M2 payments, but interest runs from the due date. Late fees apply to the quarterly GSTR-1 and GSTR-3B.
Can I upload B2C invoices in IFF?
No. IFF covers B2B invoices, credit and debit notes to registered persons, and their amendments. B2C details go in the quarterly GSTR-1.
What happens if my turnover crosses ₹5 crore in November?
You stay on QRMP for the October-December quarter and must file monthly from January 2027.
Sources
- ✓Circular No. 143/13/2020-GST on the QRMP scheme, CBIC
- ✓Create Challan: monthly payment for quarterly return, GST portal user manual.htm)
- ✓FAQs on the Invoice Furnishing Facility (IFF), GST portal
This is a summary, not legal advice. Confirm due dates for your quarter, which can be extended by notification, on gst.gov.in.

Written by
Founder, Airwix Technologies (Sleet)
Vatsal Sutariya is the founder of Airwix Technologies in Ahmedabad, the company that builds Sleet: SleetHR for HR and payroll, and Sleet Accounting for GST billing and books. He writes about GST, invoicing, business tax and choosing software for Indian businesses, and checks each rule against the official notification before it is published.
LinkedIn profile →