
Paying a Transporter: GTA Freight at 5% Reverse Charge or 18% Forward Charge After the 2025 Changes
By default, GST on goods transport agency freight is 5%, paid by you under reverse charge if you are registered, a company, firm, factory or society. If the GTA has opted for forward charge by filing Annexure V, it charges either 5% (taking no input credit itself) or 18% (with full credit). The 18% rate replaced 12% from 22 September 2025.
Freight is one of the few expenses where the buyer often owes the GST, not the supplier. Since the September 2025 rate changes, transporters' bills show 5%, 18%, or no tax at all, and accountants are unsure which is right and who pays. The answer depends on two things: whether the transporter is a GTA, and what it declared in Annexure V.
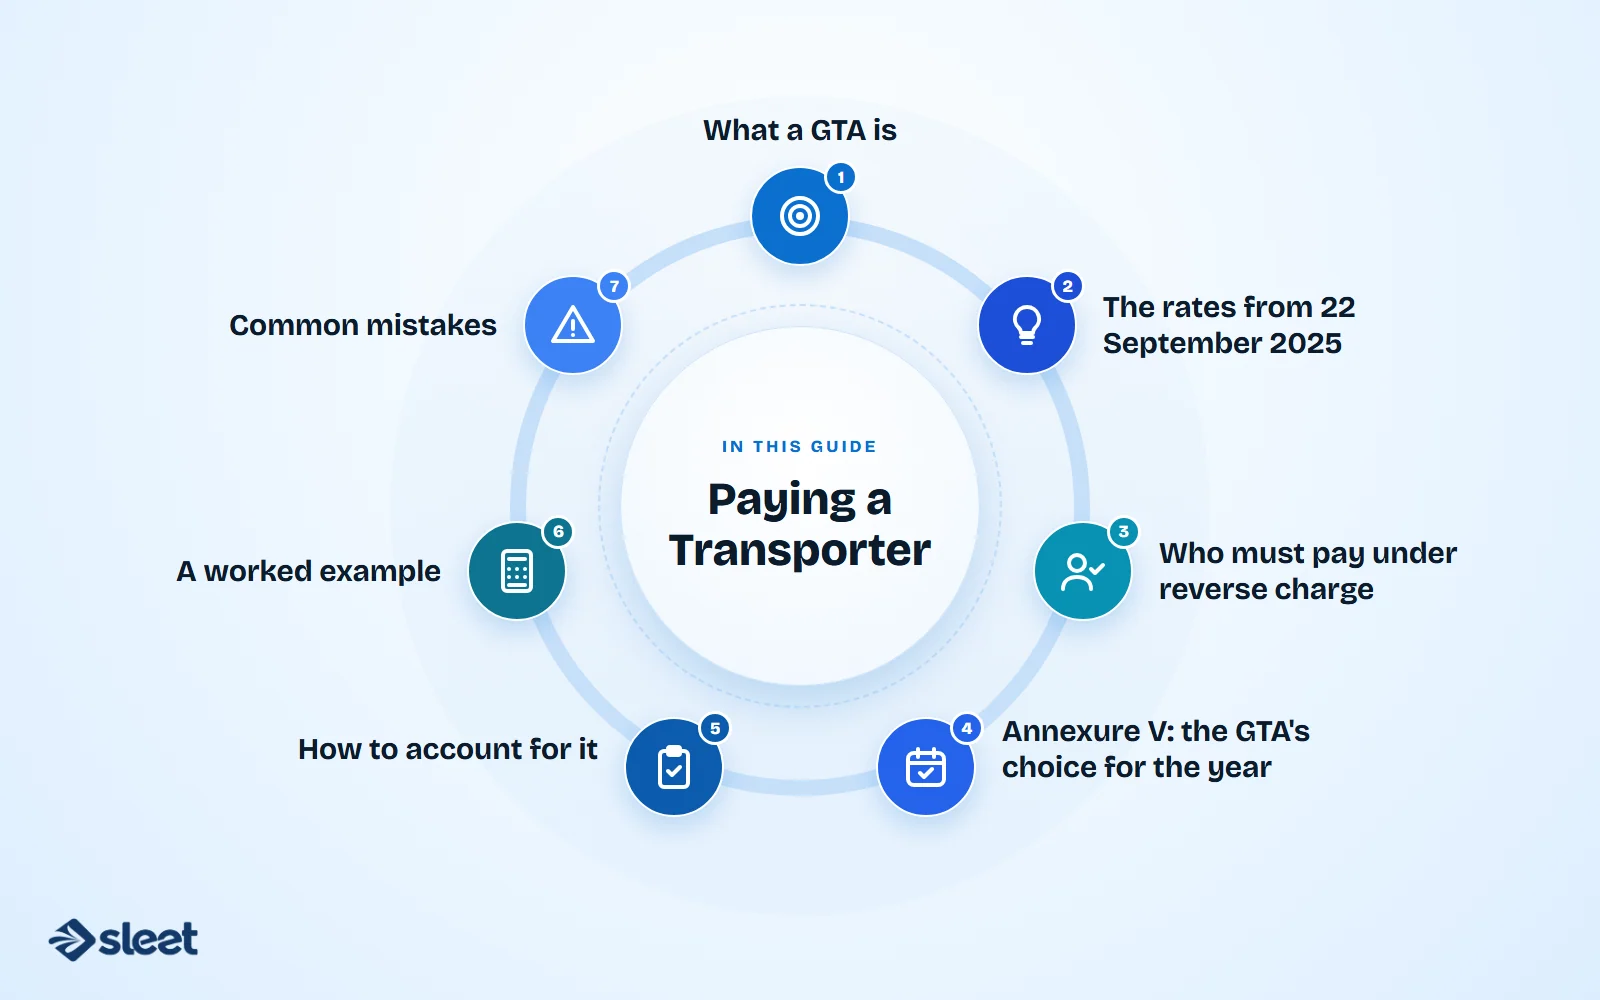
What a GTA is
A goods transport agency (GTA) is any person who provides services in relation to transport of goods by road and issues a consignment note, whatever it is called. The consignment note (LR, bilty or GR) is the test. A truck owner who just hires out a vehicle without issuing one is not a GTA; that is renting a goods carriage, taxed under a different entry.
From 22 September 2025, the definition also excludes e-commerce operators through whom local delivery services are supplied, which now fall under their own entry.
The rates from 22 September 2025
Notification No. 15/2025-Central Tax (Rate), dated 17 September 2025, amended the services rate notification. For GTA services:
| Option | GST rate | Who pays | Credit for the GTA | Credit for you |
|---|---|---|---|---|
| Reverse charge (default) | 5% | You, the recipient | Not relevant | Yes, once you pay it |
| Forward charge, lower rate | 5% | GTA | No credit on its inputs | Yes, on the invoice |
| Forward charge, standard rate | 18% (was 12% until 21 September 2025) | GTA | Full credit | Yes, on the invoice |
The 12% forward-charge option was replaced by 18% with full credit. The 5% options did not change.
If you are a registered business with taxable sales, the rate rarely changes your cost, because you get the credit either way. It matters for exempt businesses and for cash flow: RCM tax must be paid in cash.
Who must pay under reverse charge
If the GTA has not opted for forward charge, the person who pays the freight pays 5% under reverse charge, when that person is one of these:
- ✓a factory registered under the Factories Act;
- ✓a society registered under any law;
- ✓a co-operative society;
- ✓any person registered under GST;
- ✓a body corporate (company);
- ✓a partnership firm, registered or not, including an association of persons;
- ✓a casual taxable person.
GTA services to an unregistered person outside this list (for example, an individual moving household goods) are exempt. Some freight is exempt whoever pays, such as small consignments and listed goods like food grains, milk and agricultural produce; check entry 21 of Notification 12/2017-CT(Rate) before treating a bill as taxable.
Annexure V: the GTA's choice for the year
A GTA that wants to pay tax itself files a declaration in Annexure V on the GST portal (Services > User Services > Opting Forward Charge Payment by GTA):
- ✓Existing GTAs: between 1 January and 31 March of the preceding financial year. For 2027-28, the window is 1 January to 31 March 2027.
- ✓New GTAs: within 45 days of applying for registration or one month of getting it, whichever is later.
- ✓The option continues for later years until the GTA files Annexure VI to go back to reverse charge, in the same January-March window.
A GTA that pays under forward charge must put a declaration on its invoices saying so. Collect a copy of the Annexure V acknowledgement from every regular transporter in April.
How to account for it
When the GTA charges you GST (forward charge): treat it as a normal purchase. Claim the credit in GSTR-3B once the invoice is in your GSTR-2B.
When the consignment note shows no GST (reverse charge):
- Report the freight and the 5% tax in GSTR-3B Table 3.1(d) (inward supplies liable to reverse charge).
- Pay the tax in cash. Reverse-charge tax cannot be paid from the credit ledger.
- Claim the same amount as credit in Table 4(A)(3) of the same return, if the freight is for taxable business use.
- If the GTA is unregistered, issue a self-invoice and a payment voucher.
Inter-state freight attracts IGST; intra-state freight attracts CGST and SGST.
A worked example
A bicycle-parts manufacturer in Ludhiana, registered under GST and a private limited company, uses three transporters in October 2026. All three are GTAs issuing consignment notes, and all movements are within Punjab.
| Transporter | Annexure V status | Freight | GST on the bill | Paid by |
|---|---|---|---|---|
| A | Not filed | ₹80,000 | None | Manufacturer, 5% RCM |
| B | Filed, 18% | ₹50,000 | ₹9,000 | Transporter |
| C | Filed, 5% | ₹30,000 | ₹1,500 | Transporter |
Working:
- RCM on A: ₹80,000 × 5% = ₹4,000 (₹2,000 CGST + ₹2,000 SGST), reported in Table 3.1(d) and paid in cash.
- Credit on A: ₹4,000 in Table 4(A)(3).
- Credit on B: ₹9,000, from the GTA's invoice.
- Credit on C: ₹1,500, from the GTA's invoice. The "no credit" condition applies to the transporter's own purchases, not to yours.
- Total credit: ₹4,000 + ₹9,000 + ₹1,500 = ₹14,500.
- Extra cash outflow in the month: the ₹4,000 RCM, recovered as credit in the same return.
If the company forgot the RCM on A, it would owe ₹4,000 plus 18% interest, and the credit could be questioned later.
Common mistakes
- ✓Paying RCM on a transporter who already charged GST. Check the bill and the Annexure V copy.
- ✓Using the credit ledger to pay RCM. It must be paid in cash.
- ✓Treating truck hire without a consignment note as GTA. Renting a goods carriage has a separate entry.
- ✓Ignoring freight paid by the buyer under ex-works terms. Whoever pays the freight and is in the list above is the one liable.
Frequently asked questions
Can a GTA charge 5% to some customers and 18% to others?
The Annexure V option covers all the GTA services the agency supplies in that financial year. Ask each regular transporter which forward-charge rate it has chosen and expect it to apply it consistently; confirm the conditions in its declaration.
Can I claim credit on the 5% RCM I pay?
Yes, if the freight is used for taxable supplies and other conditions of Section 16 are met. The 5% rate's "no credit" condition binds the transporter, not you.
Did anything change for courier services?
Courier is not a GTA service. Courier services are taxed at 18% under heading 9968.
Sources
- ✓Notification No. 15/2025-Central Tax (Rate) dated 17 September 2025, CBIC tax information portal
- ✓GSTN advisory on filing Annexure V by GTAs opting for forward charge, Taxmann
- ✓Notification No. 06/2023-Central Tax (Rate): Annexure V window and Annexure VI, CBIC tax information portal
This is a summary, not legal advice. Confirm the current rate entries on cbic-gst.gov.in and your transporter's Annexure V status on the GST portal.

Written by
Founder, Airwix Technologies (Sleet)
Vatsal Sutariya is the founder of Airwix Technologies in Ahmedabad, the company that builds Sleet: SleetHR for HR and payroll, and Sleet Accounting for GST billing and books. He writes about GST, invoicing, business tax and choosing software for Indian businesses, and checks each rule against the official notification before it is published.
LinkedIn profile →